What is the market overview and scope of the Rigid Exoskeleton Market?
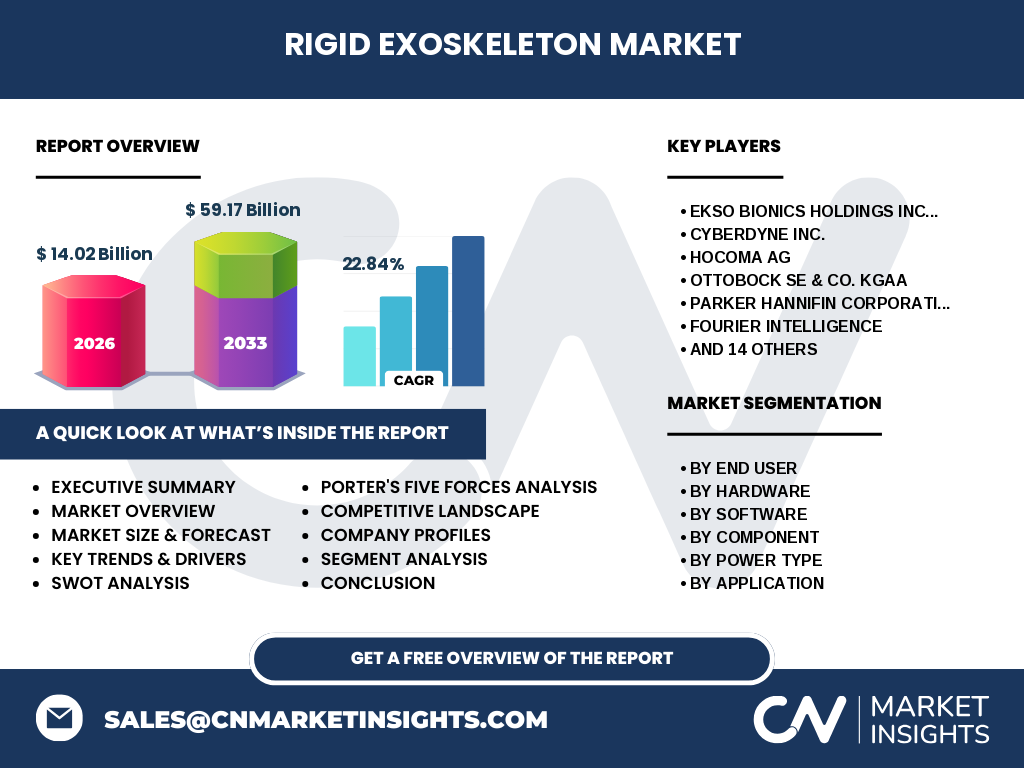
The Rigid Exoskeleton Market encompasses wearable robotic and mechanical support structures engineered to augment human strength, endurance, and mobility across defense, healthcare, and industrial sectors. Our analysis indicates a baseline market size of 14.02 Billion in 2026, driven by rising demand for ergonomic safety compliance and advanced medical rehabilitation devices.
Structural Growth Drivers and Market Constraints
Key market drivers include strict occupational safety mandates enforced by regulatory bodies like OSHA and surging military investments in soldier load-bearing systems. Conversely, primary restraints involve prohibitive acquisition costs for titanium and carbon-fiber hardware, alongside stringent FDA and CE medical certification hurdles that extend time-to-market for powered rehabilitation systems.
Emerging Trends and Growth Patterns in Rigid Exoskeletons
The industry is shifting toward AI-integrated motion control and cloud analytics software that adapt dynamically to human gait patterns. Companies are increasingly combining lightweight aluminum alloy frames with high-density battery systems to maximize operational uptime in demanding manufacturing and frontline defense deployments.
How did COVID-19 impact the Rigid Exoskeleton Market?
The pandemic severely disrupted global supply chains for crucial sensors, gyroscopes, and actuators, temporarily stalling clinical trials and industrial deployments. However, post-COVID recovery has accelerated exponentially, as logistics hubs and defense contractors prioritize automated ergonomic solutions to mitigate labor shortages and enhance operational resilience.
Competitive Benchmarking and Market Concentration
The Rigid Exoskeleton Market industry trends reveal a consolidating landscape dominated by pioneers like Ekso Bionics, CYBERDYNE, and Lockheed Martin. Market concentration is moderate-to-high in medical robotics due to IP barriers, while industrial applications see aggressive competition from automotive-backed innovators like Hyundai Motor Company.
Executive Summary of the Rigid Exoskeleton Market
Our comprehensive research positions the Rigid Exoskeleton Market at a critical inflection point, scaling from 14.02 Billion in 2026 to a projected 59.17 Billion by 2033. Propelled by a robust CAGR of 22.84%, market expansion is anchored by technological convergence in actuators, power systems, and real-time tracking software.
Market Forecast and Valuation Trajectory (2027 to 2033)
Based on our econometric modeling, the market is poised for hyper-growth, surging from its 2026 baseline to reach 59.17 Billion by 2033. This expansion represents a remarkable CAGR of 22.84%, driven by massive scaling in industrial manufacturing adoption and defense modernization programs worldwide.
Segmentation Analysis: Hardware, Software, and End Users
Market segmentation spans hardware (actuators, sensors, structural frames), software (AI assistance, motion control), power types (passive versus powered), materials (titanium, carbon fiber), and end users (defense, healthcare, industrial). Industrial and healthcare segments lead volume demand, while powered systems capture higher revenue shares due to embedded sensor complexity.
Geographic Distribution and Regional Performance
Regional performance is spearheaded by North America, supported by robust defense budgets and stringent OSHA ergonomics standards. Meanwhile, Asia-Pacific represents the fastest-growing frontier, fueled by rapid industrialization in manufacturing hubs across Japan, South Korea, and China, alongside aging demographic pressures.
In-Depth Regional Review and Localized Market Constraints
North America dominates due to early-adopter defense contracts with primes like Lockheed Martin. Europe maintains a strong foothold in medical rehabilitation, anchored by clinical adoption in Germany and France. Asia-Pacific growth is propelled by localized automotive manufacturing giants integrating industrial exoskeletons to combat workforce aging.
Strategic Positioning of Leading Companies
Industry leaders deploy distinct strategic moats: CYBERDYNE and Ekso Bionics focus on proprietary neuro-rehabilitation software, whereas German Bionic Systems and Levitate Technologies target logistics and manufacturing with passive and powered industrial solutions. Strategic partnerships with automotive and logistics conglomerates remain the primary growth lever.
Porter's Five Forces Analysis of the Industry
Threat of new entrants is moderate due to high R&D costs and regulatory hurdles. Bargaining power of suppliers for high-grade titanium and specialized actuators is significant, while buyer power remains moderate as enterprise clients prioritize ergonomic efficacy over cost minimization in safety-critical environments.
SWOT Analysis of the Rigid Exoskeleton Sector
Strengths include high strength-to-weight ratios and advanced AI integration. Weaknesses involve high hardware costs and limited battery lifespans. Opportunities lie in aging demographic healthcare needs and logistics automation. Threats include stringent regulatory compliance delays and macroeconomic supply chain volatility.
Value Chain Analysis: From Raw Materials to End-Users
The value chain flows from raw material suppliers providing carbon fiber and titanium structures to component manufacturers producing sensors, gyroscopes, and actuators. System integrators then assemble powered and passive units, distributing them through specialized B2B channels to healthcare clinics, defense agencies, and industrial manufacturing plants.
Investment Insights and High-Potential Areas
High-potential investment zones center around AI-based assistance software and high-density battery systems that extend operational runtime. Venture capital and strategic funds should target firms solving power-weight trade-offs and achieving scalable clinical reimbursement pathways.
Conclusion and Strategic Key Takeaways
The trajectory to 59.17 Billion by 2033 underscores the sector's transition from experimental tech to mission-critical infrastructure. Stakeholders must prioritize software adaptability and lightweight material science to capture maximum value across industrial and healthcare verticals.
Research Methodology and Baseline Estimation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with C-suite exoskeleton manufacturers, and secondary macroeconomic indicators from global health and defense organizations. This multi-layered approach ensures precise Rigid Exoskeleton Market market size validation.
Scope of the Report and Coverage Parameters
This report covers global market dynamics from 2026 through 2033, evaluating hardware, software, material types, power configurations, and end-user verticals. Limitations include unpredictable geopolitical shifts impacting defense procurement budgets and evolving healthcare reimbursement codes across emerging economies.
Recent Developments and Industry Announcements
Recent strategic moves feature major commercial partnerships between industrial exoskeleton providers and global logistics giants for warehouse deployment. Concurrently, medical innovators have secured key FDA clearances for advanced AI-driven rehabilitation software, accelerating clinical adoption across North American hospital networks.